
Keeping track of a homeowners association’s finances can quickly become overwhelming, especially for volunteer board members or managers without a background in accounting. From collecting dues and paying vendors to preparing reports for annual meetings, every transaction matters—and mistakes can be costly. That’s where specialized HOA accounting software comes in.
In this guide, we’ll explore what sets HOA accounting apart, why dedicated software is a game-changer, and how to find the right fit for your community.
What is HOA accounting software?
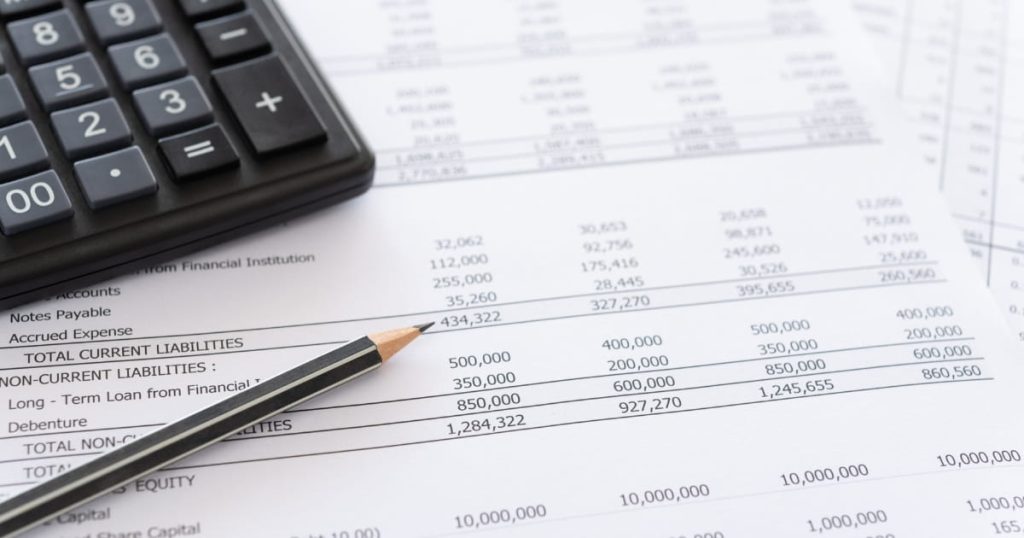
HOA accounting software is a digital platform designed specifically for the financial management needs of homeowners associations. Unlike general accounting tools, which are built for a wide range of businesses, HOA accounting software streamlines tasks unique to community associations—such as tracking member dues, managing reserve funds, and handling special assessments.
While general accounting platforms can handle basic bookkeeping, they often lack built-in features for:
- Dues and assessment tracking by unit or member
- Automated late fee calculation
- Managing multiple bank accounts for operating and reserve funds
- Generating HOA-specific financial reports for board meetings
Why HOAs need specialized accounting tools?
HOAs are responsible for managing not just money, but also trust and transparency within their communities. Here’s why specialized accounting tools are essential:
- Unique financial management challenges: HOAs must track a variety of income sources (like dues, fines, and special assessments) and expenses (maintenance, insurance, utilities, etc.), often across multiple bank accounts.
- Compliance and reporting: State laws and governing documents require accurate, timely financial reports—sometimes with specific formats not supported by generic software.
- Transparency: Homeowners expect clear records of how their dues are spent. Specialized software makes it easier to produce detailed statements and audit trails.
- Lien and foreclosure tracking: Managing delinquent accounts and legal processes is easier with built-in tools designed for HOAs.
Compared to generic accounting solutions, HOA-specific software offers:
- Automated member invoicing and payment tracking
- Board-friendly financial reporting
- Document storage for governing documents and meeting minutes
- Integration with community communication tools
These features help board members and managers avoid costly errors, improve transparency, and maintain community trust.
What is the chart of accounts for the homeowners association?
A chart of accounts is an organized list of all the financial accounts used by an HOA to categorize income, expenses, assets, and liabilities. It’s the backbone of any accounting system, providing structure for all financial transactions.
Typical accounts in an HOA chart of accounts include:
- Income: Member dues, late fees, special assessments, rental income
- Expenses: Landscaping, repairs, utilities, insurance premiums, legal fees
- Assets: Operating bank accounts, reserve funds, accounts receivable
- Liabilities: Accounts payable, prepaid dues, outstanding loans
For a better understanding of these expenses, our guide on HOA fees typical cost explains common HOA charges, what they cover, and how they vary between communities.
HOA accounting software simplifies the management of these accounts by:
- Pre-populating standard HOA account categories
- Allowing customization to fit your community’s needs
- Automating transaction posting and reconciliation
- Generating reports by account type for clear oversight
A well-structured chart of accounts makes it easier to track spending, prepare budgets, and demonstrate compliance with your governing documents and state law.
What are the methods of accounting in HOA?
HOAs typically use one of three accounting methods to record their financial activity:
- Cash basis: Income and expenses are recorded only when money actually changes hands.
- Accrual basis: Income and expenses are recorded when earned or incurred, regardless of when money is received or paid.
- Modified accrual: A hybrid approach, often used by nonprofits, that records income when earned but some expenses when paid.
The chosen method affects how financial statements look and how income and expenses are reported to members and regulators.
HOA accounting software supports these methods by:
- Allowing you to select your preferred accounting method
- Automating the correct timing of income and expense recognition
- Generating reports that match your method for consistency and compliance
Should HOA use cash or accrual accounting?
- Cash accounting is simpler and may work for very small HOAs with minimal transactions. It’s easy to understand but can obscure the true financial position if bills or dues are pending.
- Accrual accounting gives a more accurate picture of the HOA’s financial health, since it records obligations and income when they occur—not just when money moves. This is often recommended for larger communities or those with more complex finances.
Pros of cash accounting:
- Simplicity
- Easier for volunteer boards
Cons of cash accounting:
- Can misrepresent financial obligations
- Not always accepted by auditors or state law
Pros of accrual accounting:
- Provides a clearer financial snapshot
- Preferred by accountants and often required for larger HOAs
Cons of accrual accounting:
- More complex to manage without software
Some HOAs may find themselves needing to switch methods as the community grows or as regulatory requirements change. Modern accounting platforms can facilitate this transition by providing historical data in both formats and offering training resources to help board members understand the implications of each approach.
What is the best accounting method for HOA?
Industry experts and many state statutes recommend accrual accounting for most HOAs, especially those with significant assets or multiple revenue streams. Accrual accounting aligns with best practices for transparency and financial planning.
HOA accounting software can take the guesswork out of compliance by:
- Automating accrual entries and adjustments
- Generating reports that meet board, member, and regulatory expectations
- Scaling with your community’s needs, whether you’re a small or large HOA
For small HOAs, cash accounting may be sufficient—but software that can adapt as your needs grow is a smart investment.
In addition, the ability to track and report on both operating and reserve funds using the accrual method can help HOAs demonstrate prudent stewardship of community assets. This is particularly important when planning for major repairs or improvements to common areas, as it ensures that funds are available when needed and that the association can meet its obligations without resorting to special assessments or loans. Boards should regularly review their accounting method and consult their governing documents and state law to ensure ongoing compliance and financial health.
What is the best accounting software for HOA?
Several top HOA accounting software options stand out for their features, usability, and support. Here are some leading choices:
- AppFolio Property Manager: Comprehensive solution with accounting, communication, and maintenance tracking. Best for medium to large HOAs.
- Buildium: Offers robust accounting, online payments, and document storage. Scalable for various HOA sizes.
- TOPS [ONE]: Designed specifically for HOAs, with strong reporting, bank reconciliation, and member portals.
- CINC Systems: Cloud-based platform with advanced accounting features, including integration with banks and payment processors.
- Vantaca: Focuses on workflow automation and board communication, alongside accounting functions.
Pricing and support: Most platforms offer tiered pricing based on the number of units or features. Many include free trials or demos. Customer support is typically available via phone, email, or online chat.
Free or low-cost options: Some smaller platforms or spreadsheet-based tools offer basic accounting features for free or at a low cost, but may lack advanced automation or support.
A key advantage of using dedicated HOA accounting software is the ability to manage complex financial responsibilities unique to community associations. These platforms often include features like tracking assessments, managing late fees, handling vendor payments, and generating financial statements that comply with HOA reporting standards. Many solutions also offer secure document storage, which is essential for keeping records of budgets, meeting minutes, and important correspondence accessible to board members and homeowners.
HOA accounting software can also help automate the process of tracking delinquencies and managing collections, which is critical when dealing with liens or even potential foreclosure actions. Automated reminders for dues and assessments can reduce late payments and improve cash flow, while built-in audit trails help ensure transparency and accountability for board members.
For a broader look at HOA management platforms beyond just accounting, see: Best HOA management software
What is the best accounting software for a small HOA?
For small HOAs, affordability and ease of use are key. Here are some top options:
- MoneyMinder: Designed for volunteer-run HOAs, with simple budgeting, dues tracking, and reporting. Free version available with limited features.
- QuickBooks Online (with HOA templates): Flexible and familiar, but may require customization for HOA use.
- Excel or Google Sheets: While not true accounting software, these can work for very small communities with minimal transactions—but require manual effort and lack automation.
Essential features for small HOAs:
- Simple dues and expense tracking
- Easy-to-read financial reports
- Automated reminders for payments
- Secure document storage
Small HOAs often rely on volunteers who may not have formal accounting training, making user-friendly interfaces and clear reporting especially important. Look for software that allows for easy import and export of data, customizable chart of accounts, and straightforward reconciliation with bank statements. Some platforms also offer templates for typical HOA transactions, such as collecting assessments, paying for common area maintenance, or tracking reserve funds.
Having the right HOA forms can also help board members organize assessment records, document requests, and other association paperwork alongside their accounting software.
In addition, small associations should consider whether the software allows for multiple users or board member access, so that financial oversight can be shared and transitions between treasurers are smooth. Cloud-based solutions can be particularly helpful for remote access and data backup, ensuring records are not lost if a volunteer steps down or changes occur on the board.
Is QuickBooks good for HOA?
QuickBooks is one of the most popular general accounting platforms, but it’s not built specifically for HOAs. Here’s how it compares:
Advantages:
- Familiar interface for many users
- Strong general bookkeeping and reporting tools
- Integrates with many banks and payment processors
Limitations:
- Lacks HOA-specific features like member portals, automated dues tracking, or lien management
- Requires manual setup of HOA chart of accounts and custom reports
- May not meet all compliance or reporting needs for larger HOAs
When QuickBooks may work:
- Small HOAs with simple finances
- Communities willing to customize their setup
- Boards comfortable with general business accounting tools
When to consider HOA-specific software:
- Medium to large HOAs with complex needs
- Communities needing automated communication, document storage, or integration with other HOA tools
Many HOAs find QuickBooks appealing because of its widespread use and the availability of accountants familiar with the platform. However, the lack of built-in features tailored to association management means that boards must be diligent in customizing their setup. For example, tracking owner balances, managing special assessments, or handling late fees often requires workarounds or additional manual tracking.
If your HOA needs to generate reports for annual meetings, track compliance with reserve study requirements, or manage insurance payments for common areas, HOA-specific platforms can make these tasks much easier and reduce the risk of errors.
It’s also worth noting that while QuickBooks can handle basic financial management, it does not natively support the unique reporting and documentation needs of HOAs, such as providing owners with access to their account history, automating notices for unpaid assessments, or integrating with online voting and communication tools.
What documents matter in HOA accounting?
Accurate HOA accounting relies on more than just software—it depends on understanding which documents guide your financial practices. Your HOA’s governing documents, including the Declaration of Covenants, Conditions & Restrictions (CC&Rs), bylaws, and board resolutions, outline how funds must be managed, what expenses are allowable, and the procedures for assessments and collections.
State law may also impose requirements for financial reporting, annual audits, or reserve fund disclosures, which your software should help you track and document.
Board members can explore additional HOA resources for helpful guides, templates, and practical information on managing association documents and financial responsibilities.
If you need guidance on obtaining or organizing your HOA’s financial paperwork, see: How to get HOA financial documents
Common mistakes when choosing HOA accounting software
Selecting the wrong accounting software can lead to frustration, wasted time, and even compliance issues.
Some common pitfalls include:
- Choosing a general business platform that lacks HOA-specific features, resulting in manual workarounds and missed compliance steps.
- Overlooking the importance of secure document storage for financial records, meeting minutes, and owner communications.
- Failing to ensure the software supports multiple users or board transitions, which can disrupt financial oversight.
- Not verifying that the platform can handle the scale of your association, especially if you anticipate growth or increased financial complexity.
- Ignoring integration needs with other tools, such as online payment processors, communication platforms, or maintenance tracking systems.
Carefully reviewing your governing documents and understanding your community’s unique needs can help you avoid these mistakes and select a solution that truly fits.
Conclusion: Making sense of HOA accounting software
Choosing the right accounting software for your HOA is about more than just balancing the books—it’s about building trust, ensuring compliance, and making financial management less stressful for everyone involved. Specialized HOA accounting software can save time, reduce errors, and help your community thrive, whether you’re managing a handful of homes or hundreds of units.
No matter the size of your association, taking the time to evaluate your options and understand your legal and financial obligations can help you avoid costly mistakes. The right software, paired with clear processes and accessible records, empowers your board to make better decisions and provide transparency to your members. If your HOA faces disputes over assessments, questions about lien procedures, or uncertainty about financial reporting standards, having reliable tools and access to expert guidance can make all the difference.
Take the next step for your community
Ready to simplify your HOA’s finances and boost transparency? Explore our membership plans for access to expert resources, practical guides, and—at the Pro and HOA Team levels—unlimited personal support from an experienced HOA attorney. The right tools and guidance can help your community stay on track and avoid costly mistakes.